

Last reviewed: 13 October 2026
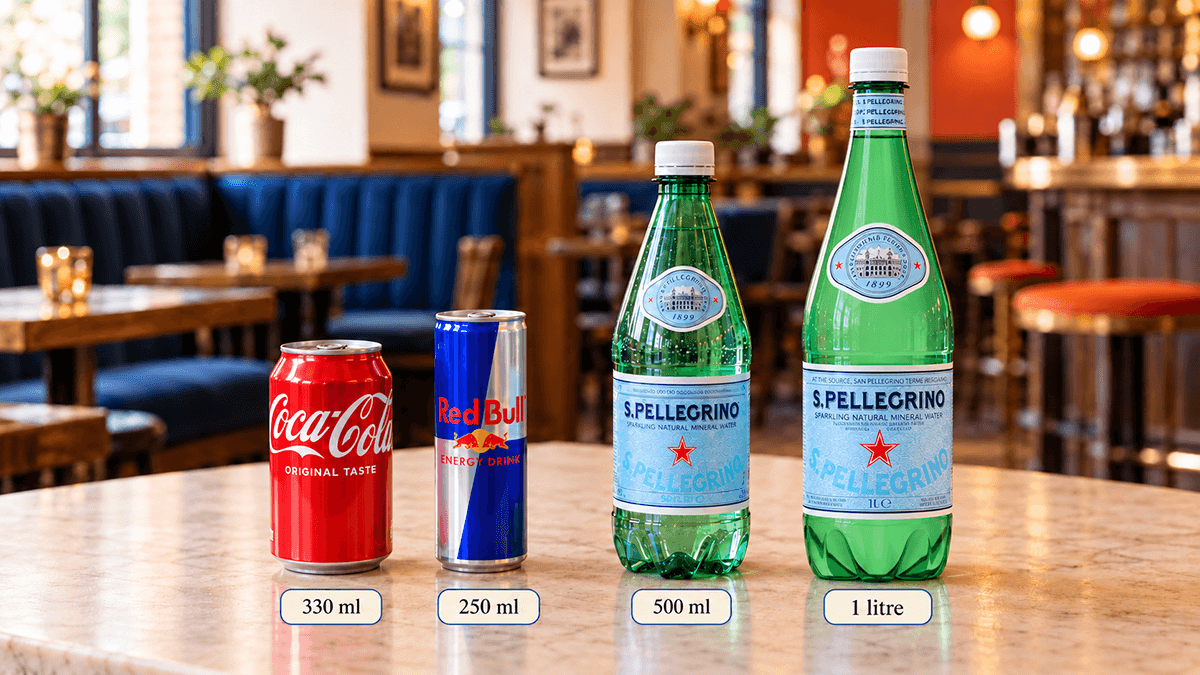
A London bar might stock the same soft drink in a can, single-use PET bottle, reusable bottle and glass bottle. The liquid may be similar, but its Deposit Return Scheme (DRS) treatment can differ with every format. Review each product and container combination for its material, capacity, intended use and country of supply; the drink category alone will not answer the question.
Four checks for a London venue
Under the standard England, Northern Ireland and Scotland scope, a container will generally be included when all these tests are met:
- It is single use. Reusable containers sit outside the standard England and Northern Ireland scope.
- It is made wholly or mainly from PET plastic, aluminium or steel. “Plastic” is not precise enough: HDPE containers, for example, are outside the stated England and Northern Ireland scope.
- It holds at least 150ml and no more than 3 litres. Both limits are included.
- It is supplied in a nation where that material is covered. England, Northern Ireland and Scotland share the core PET, aluminium and steel scope. Wales also includes glass, with special transition arrangements.
Statutory exceptions apply, so use current product information where a stock-keeping unit (SKU) is unclear.
A compact stock eligibility matrix
| Container or product format | Material | Size and use tests | England, Northern Ireland and Scotland | Wales difference |
|---|---|---|---|---|
| Canned beer or soft drink | Aluminium or steel | Single use and 150ml–3 litres inclusive | Generally in scope if all tests and no exception apply | Metal is included; confirm current Welsh product detail before launch |
| PET bottled water or soft drink | PET plastic | Single use and 150ml–3 litres inclusive | Generally in scope if all tests and no exception apply | PET is included; confirm current Welsh product detail before launch |
| Reusable drinks container | Varies | Intended for reuse | Outside the stated England/NI standard scope | Check current Welsh rules separately |
| HDPE drinks bottle | HDPE plastic | Any size | Outside the stated England/NI scope | Check current Welsh rules separately |
| Glass drinks bottle | Glass | Single use and 150ml–3 litres inclusive | Outside the core England/NI/Scotland scheme | Included from launch, but with the glass transition explained below |
| Liquid-medicine container | Varies | Contains liquid medicine | Excluded from the stated England/NI scope | Check current Welsh rules separately |
| Drink flavouring or sweetener product | Varies | Used only to flavour or sweeten a drink | Excluded from the stated England/NI scope | Check current Welsh rules separately |
These are classification prompts rather than SKU decisions. A 330ml beer can and 500ml PET water bottle would usually meet the material and size tests, but must still be single use and not excepted.
The current GOV.UK responsibilities guidance gives more detail on the England and Northern Ireland scope. Our DRS overview for pubs, bars and restaurants explains the wider scheme.
Why Wales needs its own check
Glass is outside the core England, Northern Ireland and Scotland scheme, but Wales will include single-use glass drinks containers from 150ml to 3 litres inclusive from October 2027. For a four-year transition, Welsh glass will carry a 0p deposit and need no DRS-specific label. A deposit is not due until October 2031.
A glass beer bottle therefore should not be described as carrying 20p throughout the UK in 2027. The Welsh Government’s appointment statement explains the transition. Welsh venues should check current national guidance before classifying stock.
How staff will recognise standard scheme stock
Standard in-scope packaging will use a scheme logo and registered return code or barcode. Exchange for Change, the scheme administrator, has published logo and material specifications. These features will help venues alongside supplier and product data, but statutory exceptions mean they are not the only test. Packaging design and barcode registration remain producer responsibilities.
What about stock produced before launch?
On 30 September 2026, Exchange for Change said finished products manufactured and filled before 1 October 2027 would remain outside DRS and could be sold after launch in England, Northern Ireland and Scotland. Possible added flexibility for older packaging tied to pre-launch orders was still under discussion, while Welsh transition arrangements would follow.
Check the transition position against the latest regulations and regulator guidance before launch. Do not assume that tentative flexibility has been confirmed.
Our guide to deposits, takeaway sales and empty containers covers charging and recovery. The venue preparation guide covers launch planning.
Frequently asked questions
Will every plastic drinks bottle carry a deposit?
No. In the standard England and Northern Ireland scope, it must be single use, mainly PET and hold 150ml to 3 litres inclusive. HDPE and reusable containers are outside that stated scope; other exclusions can apply.
Are 150ml containers included, and what about 3-litre containers?
Yes. Both limits are inclusive, provided the material, single-use and national tests are also met.
Will glass beer and wine bottles carry 20p?
Not in England, Northern Ireland or Scotland. Wales includes single-use glass drinks containers from 150ml to 3 litres inclusive from October 2027, but they carry 0p during the four-year transition; a deposit is not due until October 2031. No later amount is assumed here.
How will staff recognise a DRS container?
Standard scheme stock will use a scheme logo and registered return code or barcode. Staff should also use current supplier and product information, especially for older stock and exceptions.
Review formats line by line
Record each container’s material, capacity, single-use status and country of supply. Ask suppliers about unclear lines as product data becomes available. Champers customers can discuss affected stock and future product information with the team, without assuming a particular collection or credit process.



 Group


